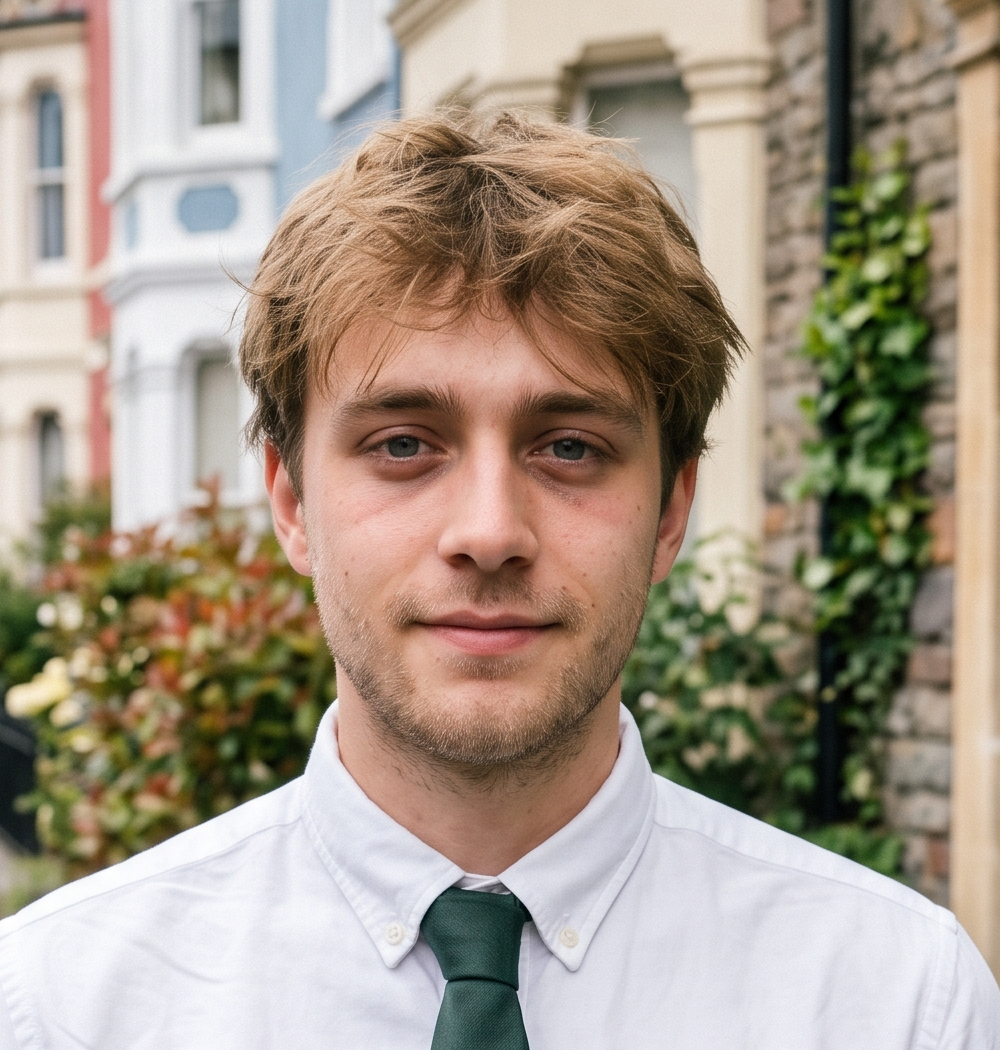
James, 21
The "Unwilling Boomerang"
"I love my parents, but I need to be able to order a pizza at midnight without answering twenty questions. My living situation is actively killing my social life."
The Current Situation
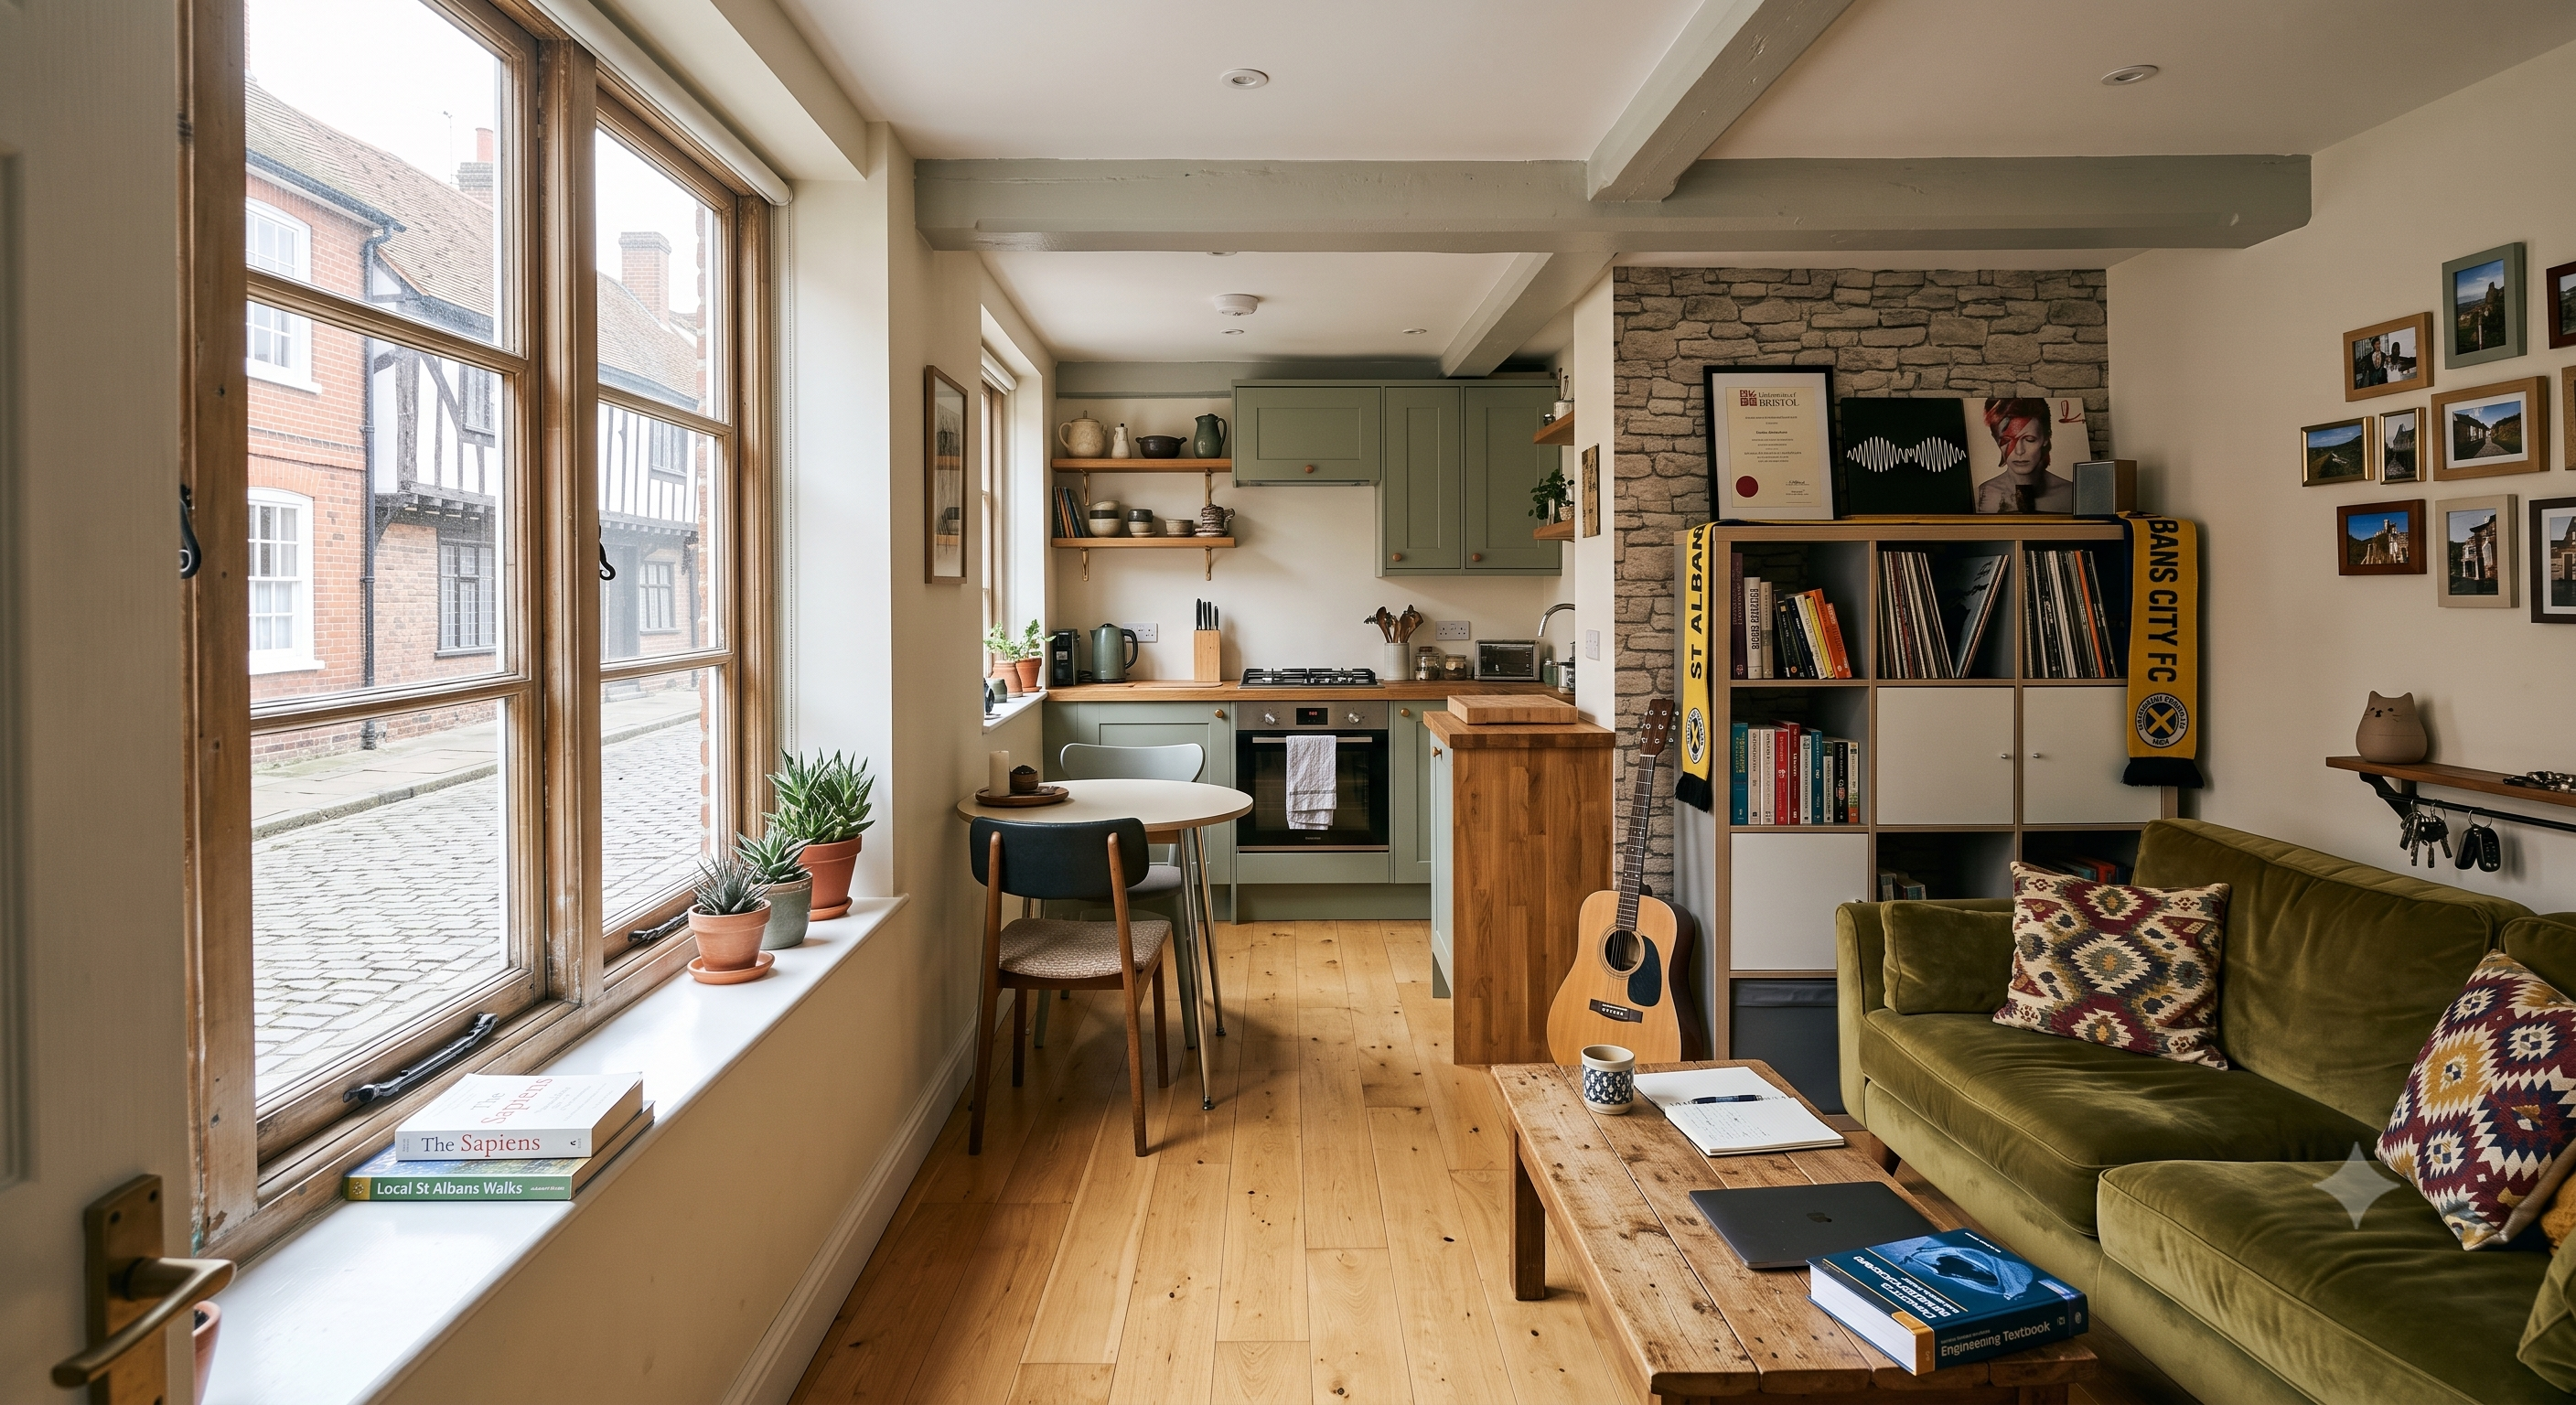
James moved back into his childhood bedroom after graduation. His parents charge him a small amount of board, but he feels like a teenager with an adult salary. He wants to buy a £200,000 one-bedroom flat in St Albans.
Income & Debt
£32,000 salary
£53,000 student loan
Outgoings
£800 per month rent
£1,250 per month lifestyle
Savings
£500 in bank
£0 in pension
The Goal
£200,000
1-bed flat
The Base Outcome
If James changes nothing, targeting a house purchase is still his best financial strategy. However, he will be 38 years old before he can afford to buy his flat—four years later than the current UK average for first-time buyers.
Buying > Renting
Even buying at 38, he generates £396,000 more in lifetime wealth compared to renting for life, largely due to escaping rent costs in retirement.
How can James speed up the process?
Age 38 feels a long way off for a 21-year-old. Our model tested different life choices and interventions to see how James could buy his home sooner.
The "Bank of Mum & Dad"
If James's parents are in a position to help, transferring wealth early in life has a massive multiplier effect.
Scenario A: Free Rent
If his parents stop charging the £800 per month rent.
He buys 11 years earlier.
Scenario B: A £10,000 Gift
A one-off lump sum contribution to his deposit.
A £10k gift grows to create nearly 7x that amount in lifetime wealth.
Changing Lifestyle Habits
James currently spends £1,250 a month on clothes, nights out, and trips. What happens if he embraces a frugal lifestyle?
Scenario C: Cutting Expenses
Reducing discretionary spending from £1,250 down to £500 a month.
"How you spend the money you have makes a significant impact on both overall wealth accumulation over your lifetime and when you can buy a house."
By cutting back, he buys 11 years earlier and dramatically increases his final net worth from the base £1.35M.
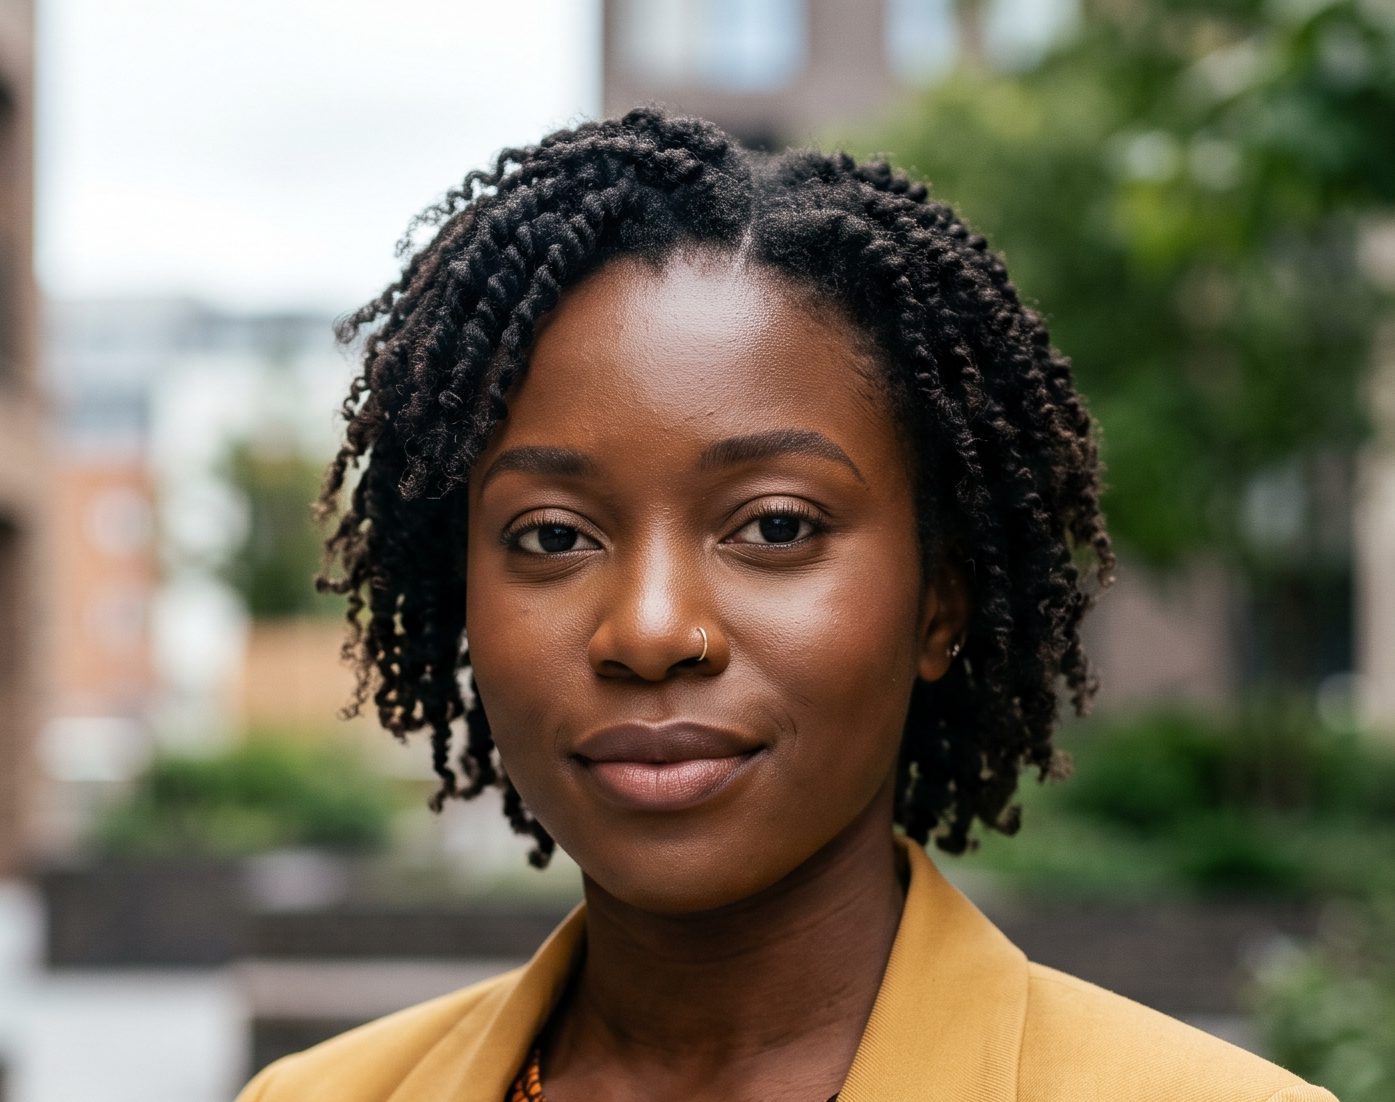
Next Scenario: Becky, 24
The "Independence Protector". Becky rents her own flat but faces a choice between keeping her space and ever being able to afford a home. See how her choices compare to James's.
Ready to see your own projection?
You don't have to guess. Use the calculator to explore how your rent, spending habits, and target house price affect your long-term wealth.